It’s one of the most common questions buyers are asking right now: should I buy a new home now, or wait for the market to shift? Should I hold off until rates drop? Or is this actually the right moment to make a move?
The honest answer is that timing the market is almost impossible, but understanding what you’re actually waiting for can help you make a smarter decision. And for many buyers right now, the case for buying sooner rather than later is stronger than it might appear.
You Can Always Refinance. You Can’t Renegotiate Your Price.
This is the piece of the conversation most buyers miss.
When interest rates eventually drop, one of two things tends to happen. Either you refinance and get the benefit of the lower rate, or the market heats up so quickly that you’ve already lost the opportunity you were waiting for.
The problem with waiting is that lower rates bring more buyers into the market. More buyers competing for the same homes drives prices up. So the monthly savings you expected from a lower rate can get absorbed by a higher purchase price. For buyers asking whether they should buy a new home now, the most important number to focus on is not the rate but the price.
A lower rate is something you can capture later through refinancing. A lower purchase price on the right home is something you can only lock in when you buy.
And the impact of a lower purchase price goes beyond the mortgage. In California and Nevada, property taxes are calculated based on what you paid for your home. A higher purchase price means a higher tax base, and that’s a number that follows you for the entire time you own the home. Buyers who lock in a lower price today aren’t just saving on their monthly payment. They’re locking in a lower property tax bill for years to come
New Construction Incentives Change the Math
In higher-rate environments and amid market shifts, new construction builders like Tim Lewis Communities offer incentives that make buying significantly more attainable than the headline rate suggests. Rate buydowns, closing cost credits, appliance packages, free backyard landscaping – these are real dollars that directly reduce what you pay each month or what you need to bring to closing.
According to the National Association of Realtors, new home buyers who take advantage of builder-offered rate buydowns can save hundreds of dollars per month during the critical first years of homeownership. On a resale home, that kind of flexibility simply doesn’t exist.
There’s also an important reality about incentives: they tend to shrink or disappear as market conditions improve. The incentives available today reflect a market where builders are motivated to help buyers move forward. When the market heats up, those incentives typically go away, and buyers who waited often find themselves paying more for less.
What Is Your Why Right Now?
For buyers still asking should I buy a new home now, the answer often comes down to a simpler question: why do you want to buy in the first place?
Maybe your family is growing, and you need more space. Maybe you’re finally ready for a home office that actually works. Maybe mom or dad is moving in, and you need a layout that gives everyone room. Maybe you’ve simply been working toward a home that feels like it was built for the life you actually want to live.
Those reasons don’t get better with waiting. And in most cases, the home that checks those boxes isn’t going to get cheaper the longer you hold off.
Understanding your why is what makes the timing conversation make sense. If your reasons for buying are real and present, waiting for the perfect moment can cost you more than you save.
The Equity Argument for Buying Now
One thing the wait-for-rates conversation often overlooks is what happens to home values in the meantime.
When rates drop, and more buyers enter the market, demand increases. Increased demand supports higher home prices. That means the home you purchase today at today’s price could be worth meaningfully more by the time rates improve, building equity in a way that waiting simply can’t replicate.
In California and Nevada, home values have consistently appreciated over time, even through periods of rate volatility. Buyers who got in earlier have consistently benefited more than those who waited for the perfect conditions that never quite arrived.
Buying a home is one of the few ways to build equity while you live your life. Waiting to buy is one of the few ways to let that opportunity pass.
What New Construction Offers That Resale Can’t
Beyond the financial reasons, there’s a practical one.
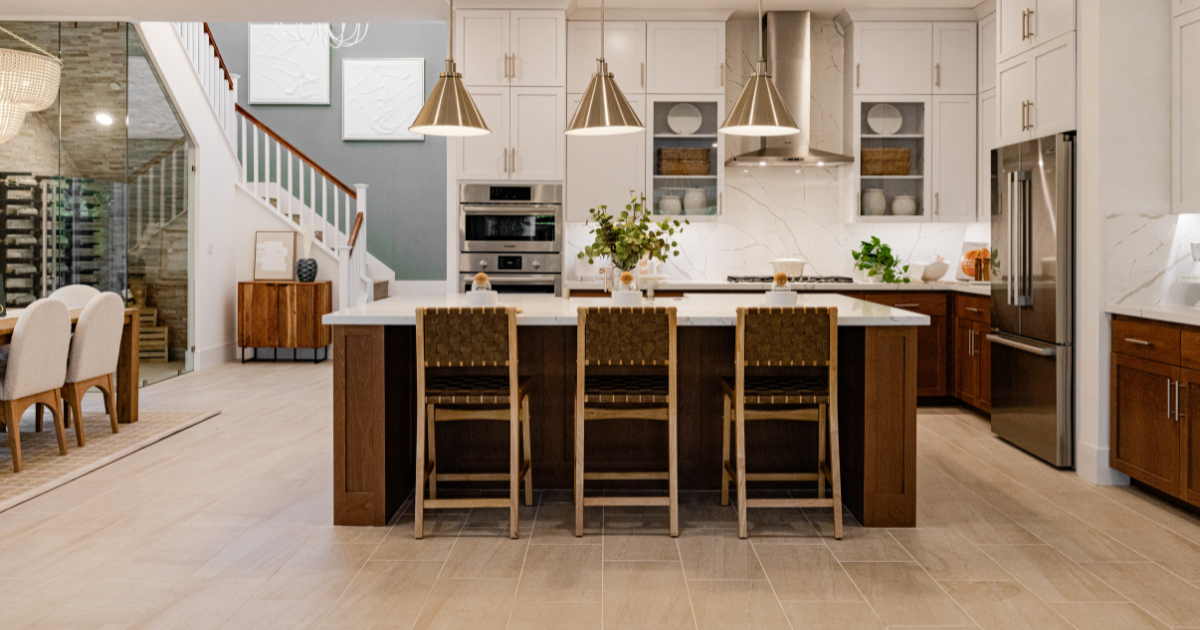
New construction gives you something resale homes can’t: a home that’s never been lived in, built to current energy efficiency standards, backed by a builder warranty, and designed around the way people live today. No deferred maintenance. No competing offers. No surprises from a home inspection.
At Tim Lewis Communities, every home is also designed specifically for its community, not pulled from a shared catalog and built the same way everywhere. The architecture reflects the neighborhood. The floorplans reflect how real families live. The finishes are selected with intention.
Communities across Northern California and Nevada include:
- Magnolia at Granite Bay: One-acre luxury homesites in gated Granite Bay
- The Woods at Crowne Point: Gated luxury in Rocklin with rare walk-out basement options
- Morgan Place: New construction in Roseville with no Mello-Roos
- The Courtyards at Arrowcreek Parkway: Low-maintenance living in Southwest Reno
- Drift at Riverfront: Modern condominiums and townhomes in Petaluma from the low $600s
- Skyview: Rocklin’s newest luxury community
Quick Move-In homes are available now across select communities, giving buyers the benefits of new construction on a move-in-ready timeline.
Should You Buy Now?
If you’ve been asking yourself should I buy a new home now, you already know the answer is personal. But the financial case — lower purchase price, locked-in tax base, builder incentives that won’t last, and equity that starts building from day one — points in one direction for most buyers right now.
You can refinance when rates improve. You can’t go back and buy the same home at today’s price. And you can’t get back the equity you would have been building in the meantime.
The best time to buy a home was always the moment it made sense for your life. For many buyers right now, that moment is here.
Frequently Asked Questions
Should I wait for interest rates to drop before buying a new home?
Waiting for rates to drop can be a risky strategy. When rates fall, more buyers enter the market, competition increases, and home prices tend to rise. You can always refinance to a lower rate later, but you can’t renegotiate the purchase price of a home you already bought. Locking in today’s price and refinancing when conditions improve is often the smarter long-term move.
Will home prices go down when interest rates drop?
Not necessarily. Lower rates typically increase buyer demand, which puts upward pressure on home prices. Many buyers who wait for rates to drop find that prices have risen enough to offset the monthly savings from the lower rate.
What makes new construction a smart buy in a higher-rate environment?
New construction in higher-rate environments comes with builder incentives, rate buydowns, closing cost credits, appliance packages, and more that can significantly reduce your monthly payment or out-of-pocket costs at closing. These incentives are typically not available on resale homes and tend to shrink as market conditions improve.
What is a rate buydown and how does it help?
A rate buydown is when the builder pays to temporarily or permanently lower your interest rate. A 2/1 buydown, for example, gives you a rate that’s 2% lower in year one and 1% lower in year two, saving you hundreds of dollars per month during the first years of homeownership.
What Quick Move-In homes are available at Tim Lewis Communities right now?
Tim Lewis Communities has Quick Move-In homes available across multiple communities in Northern California and Nevada, including Magnolia at Granite Bay, The Woods at Crowne Point, Morgan Place, The Courtyards at Arrowcreek Parkway, and Drift at Riverfront. Visit our Quick Move-In page to see current availability.